Foreign National Program without:
Residency, Social Security or Income in the US
USDA Loans for moderate income Families
0% down payment - 100% financing
All Government Loan Programs
FHA, USDA and VA
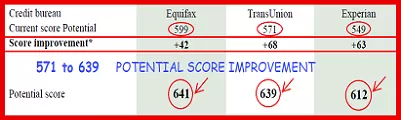
Ask us about our program
To improve your credit scores...
Starting with only:
580 Credit Scores!!!
Don't worry and submit your information
We will help you.
Contact us to analyze your options.
Don't worry and submit your information
We will help you.
Upto 90% financing for
Purchases of up to $830,000.
Purchasing a home and trying to figure out what home loan closing costs to expect? Next I will be discussing closing costs.
What exactly is closing cost, you might ask? Closing costs are basically expenses incurred in the process of completing the home purchase transaction which are over and above the purchase price of the property and which you are planning to buy. These closing costs slightly differ from loan to loan and though initially may not seem like such a big deal considering that you are purchasing a property that’s worth many times over closing costs can actually add up to thousands of dollars!
Before I go in detail with some of the most typical closing costs seen on most of home loan programs, I invite you to watch this video from the Consumer Financial Protection Bureau in regards Home Loan Closing Costs.
Let’s go over typical home loans closing costs generally seen in all loans:
• Loan origination fee - An origination fee is an upfront fee charged by a lender for processing a new loan application, used as compensation for putting the loan in place generally between 0.5 and 1% on mortgage loans.
• Transaction Fee - The fee the lender and any mortgage broker charges the borrower for making the mortgage loan
• Warehouse Fee - A charge to a borrower when a mortgage banker or other small lender must borrow money on a short-term basis in order to loan money on mortgage loans.
• Document Review Fee – A fee paid to bank’s attorneys prior to loan closing to review legal documents related to the settlement of a property.
• Discount Points Fee - Prepaid interest on the mortgage loan. The more points you pay, the lower the interest rate on the loan and vice versa. Borrowers typically can pay anywhere from zero to two points, depending on how much they want to lower their rates. This kind of point is tax-deductible.
• Appraisal Fee – A fee which covers the cost of having a professional appraiser evaluate a home and estimate the market value of the home. The cost is often around $400 to $600 in most markets, but unique properties and remote homes can cost more to appraise.
• Credit Report Fee - A fee to pay a detailed report of an individual's credit history which lender will need to determine loan applicants' credit worthiness.
• Tax Service Fee - A fee paid to a tax service agency to look for delinquent property taxes and alert the mortgage company to prevent tax liens from existing against their mortgagors' homes. Since tax liens have priority over lender liens, banks want to ensure that they, not the state, become the owner of these properties before closing transaction.
• Flood Certification Fee - A fee that must be paid for an assessment to determine whether the property resides in a flood zone. When a residential home is found to lie within a flood zone, flood insurance is required before closing the sale.
• Document Preparation Fee - A fee that attorneys and/or settlement agents charge for the preparation of the necessary closing documents.
• Contract Processing Fee - A charge for obtaining and coordinating documentation, appraisals, employment and credit history, or any other information necessary for the lender's underwriting department and final approval.
• Lender’s Title Insurance Fee - Title insurance is an insurance policy that covers the loss of ownership interest in a property due to legal defects and is required if the property is under mortgage. The most common type of title insurance is a lender's title insurance, which is paid for by the borrower but protects only the lender.
• Title - Settlement/Escrow Fee - This fee is paid to the settlement agent or escrow holder. Responsibility for payment of this fee can be negotiated between the seller and the buyer.
• Title - Tax Certificate Fee - Fee paid to a title company to determine the status of property taxes on the property.
• Survey Fee – Fee paid to a surveyor to measure the metes and bounds of the property that you're actually buying. He'll draw a nice map of the property, showing the property line, the improvements on the property, any fences or shrubs, and any easements on record.
• Mortgage Recording Charge Fee - Fees paid to the county for recording the deed of trust and the warranty deed.
• Owner title policy - Insurance policy that covers the loss of ownership interest in a property due to legal defects which is required if the property is under mortgage.
• Underwriting fee – Fee to cover the cost of evaluating your total loan application package, including your credit report, employment history, financial documents and appraisal to complete risk assessment and thus its final approval.
• VA Funding Fee – A fee paid by a buyer or seller to insure the lender against loss through default on a VA loan.
• Upfront Mortgage Insurance Premium – MIP – A price paid by the borrower to insure the lender against loss through default with FHA loans.
• Home inspection - An examination of a real estate property's condition, usually performed in connection with the property's sale. A qualified home inspector can assess the condition of a property's roof, foundation, heating and cooling systems, plumbing, electrical work, water and sewage, and some fire and safety issues.
These are some of the most common type of closing costs. For more information on closing costs or further clarification on any matter related to mortgage loans please contact me at 281-940-2554.
Apply today with Clear Lending and find out what’s possible.
GET PRE-APPROVED ESTIMATE NOW ONLINE
Author:
Joan Gallardo
Loan Officer NMLS 367858
Realtor TREC 0640762
Cant be happier with my loan and my new house. I recommend them. I got a rate way better than my bank with which I have been with them forever. Nonetheless Clear Lending got me a better deal. Very impressed and very happy. Thanks.
Joan at Clear Lending was patient, dedicated & thorough with our transaction buying a house. We are 1st time home buyers & needed closing costs. Joan did not give up on us, showing us home after home, in so many different areas around Houston, talking to so many agents for us & helping us until we found our home. He even went the extra mile & made it right by us when the sellers left a mess in the house. Joan didn't have to do that, but he did because he genuinely cares about his clients. I'm really glad we went with him & we'll return if/when we choose to upgrade to a bigger home.
I owe it all to Joan for making our dreams come true. I never thought I would own a home, but Joan made it happen. He was there for me at all hours of the day with questions and concerns I had. Everyday he would communicate with me, on how the process was going. Joan is on top of everything and SUPER fast. If any one is the need of buying a home, I would totally recommend him!